I’m Waiting for Rates to Drop
Mortgage rates have climbed for most of this past week. Take your pick of the reason: sticky inflation, a Fed that's staying put for now, some renewed tension overseas rattling markets. The 30-year fixed mortgages is bumping up against 6.9%.
It seems like the same question is coming up for everyone: should I wait this out?
I get why. Nobody wants to lock in a rate today only to watch it drop next spring. But, let’s talk about trying to “time the market.”
If you were around for 2008, you probably remember it as the worst possible moment to buy a house. People were terrified. Prices kept falling. Anyone who bought in the middle of it looked, for a while, like they'd made a bad call.
Looking back now, most of those buyers made the best real estate decision of their lives.
I bring this up not to promise you the same outcome, nobody can promise that. But it's a useful reminder that often the best time to buy, is when everyone else is waiting. You rarely get to buy at the bottom, and know it at the time.
Rates Aren't the Only Moving Piece
Listen, if interest rates are preventing you from purchasing because your monthly payment would be too high, I get it. However waiting for rates to drop isn’t the most sound strategy.
Historically, when people wait for a better rate, this is how it goes: eventually rates ease, more buyers come off the sidelines at the same time, competition picks up rapidly, and the home you were eyeing gets dozens of offers instead of just one or two. The 2021 Los Angeles housing market is the perfect example of this — interest rates hit historic lows and suddenly homes were selling for hundreds of thousands of dollars over asking, all cash, with no contingencies. Many buyers who waited for the rate, suddenly couldn’t compete at all.
When interest rates drop, the monthly payment might come down, but the price you're competing at, goes way up. You rarely get the low rate and the quiet market at the same time.
Now, if you can afford the payment with today’s rate, remember that you can refinance down the road should interest rates ease.
What to Do Instead of Waiting
Rather than waiting to see if rates will drop, ask yourself: can I afford this house at today's rate? Do I actually want to live in it? Am I planning to stay long enough for it to count?
If the answer to all three is yes, a rate hike headline from this week shouldn't be the factor that decides for you. Rates will move again. They always do. The house either fits your life or it doesn't, and that won’t change with the news cycle.
If you want to run a few numbers, I have a resource I can send you to help sort out what your monthly payment would like at today’s rates. Shoot me a note and I’ll send it your way.
Until next time,
Dana
____________________________
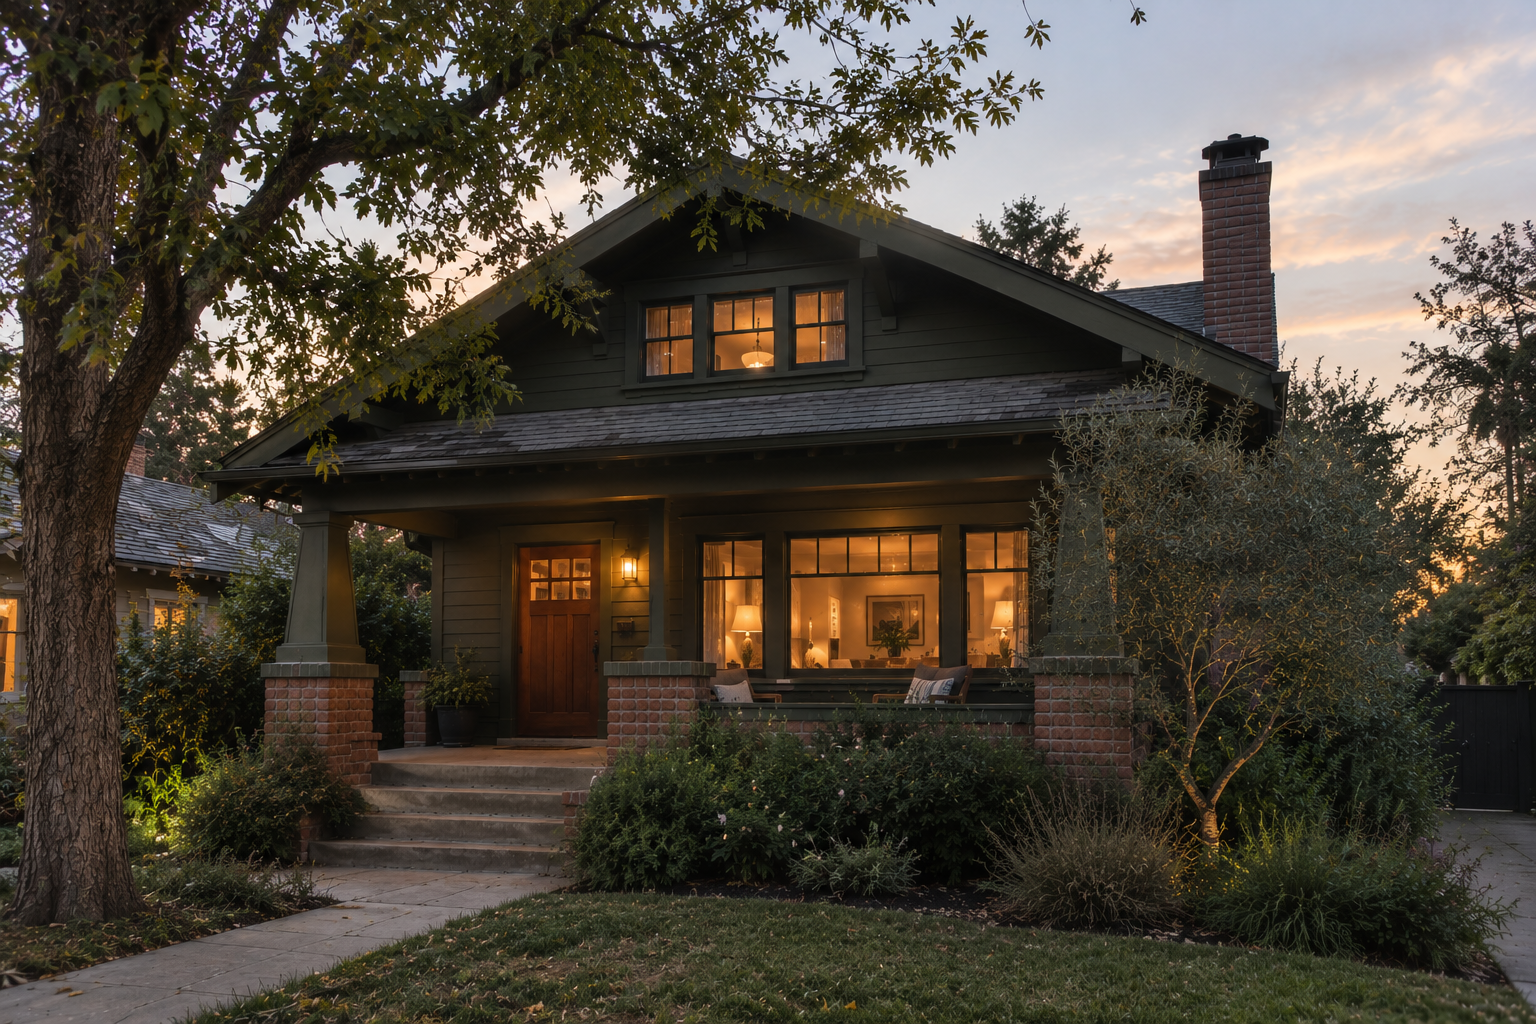
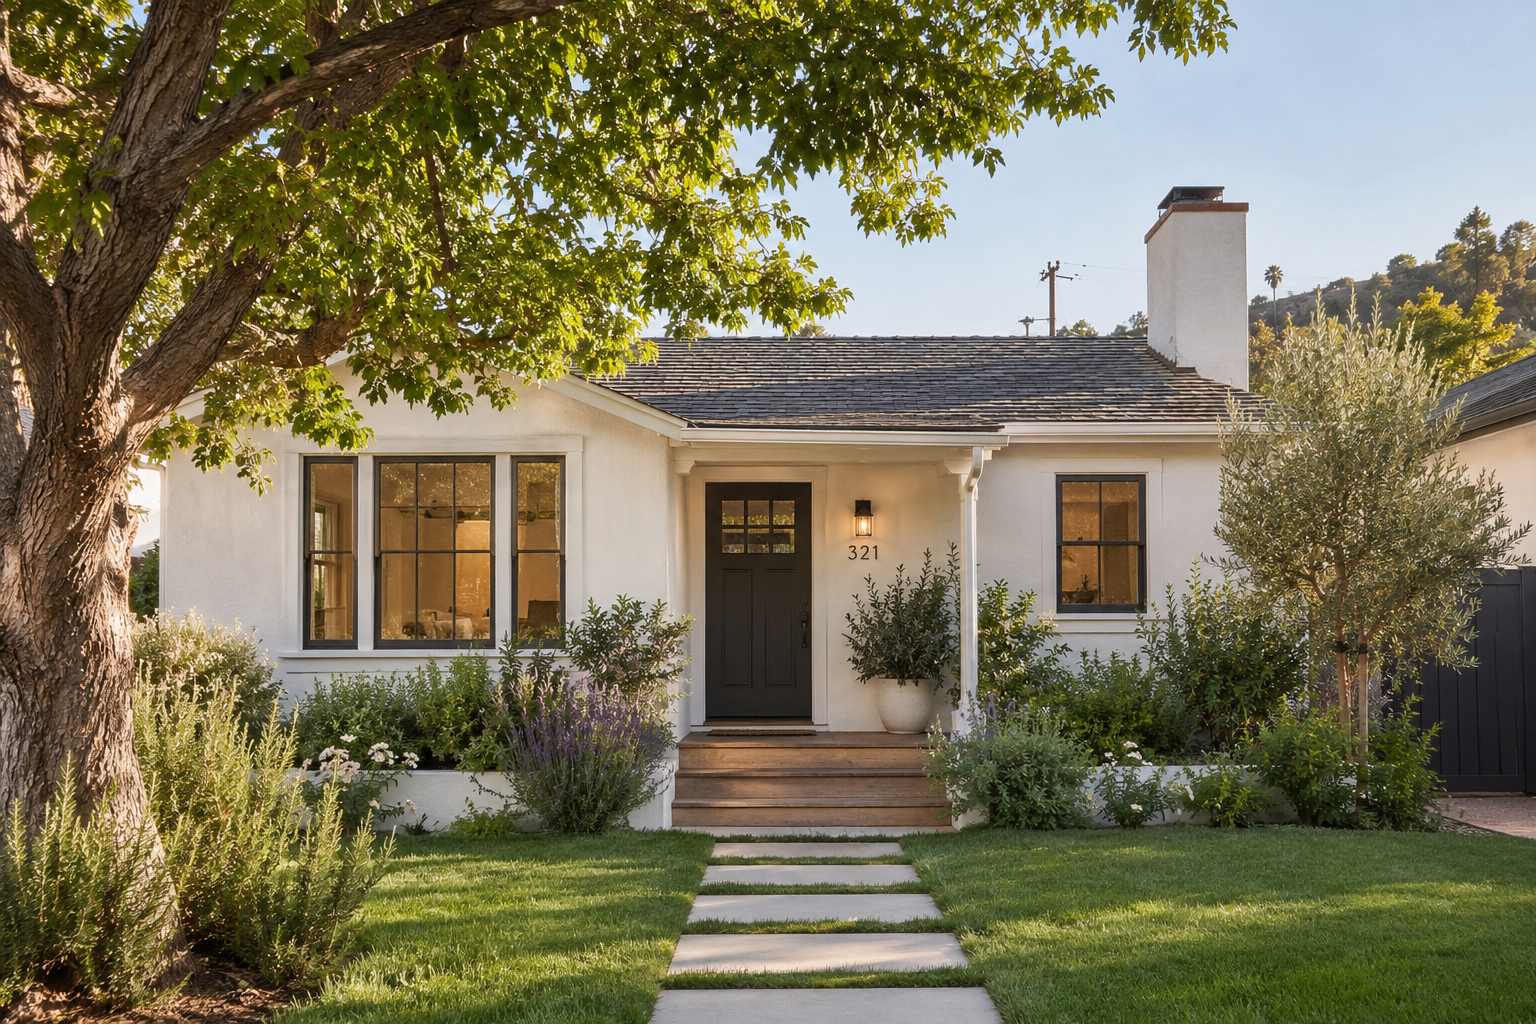
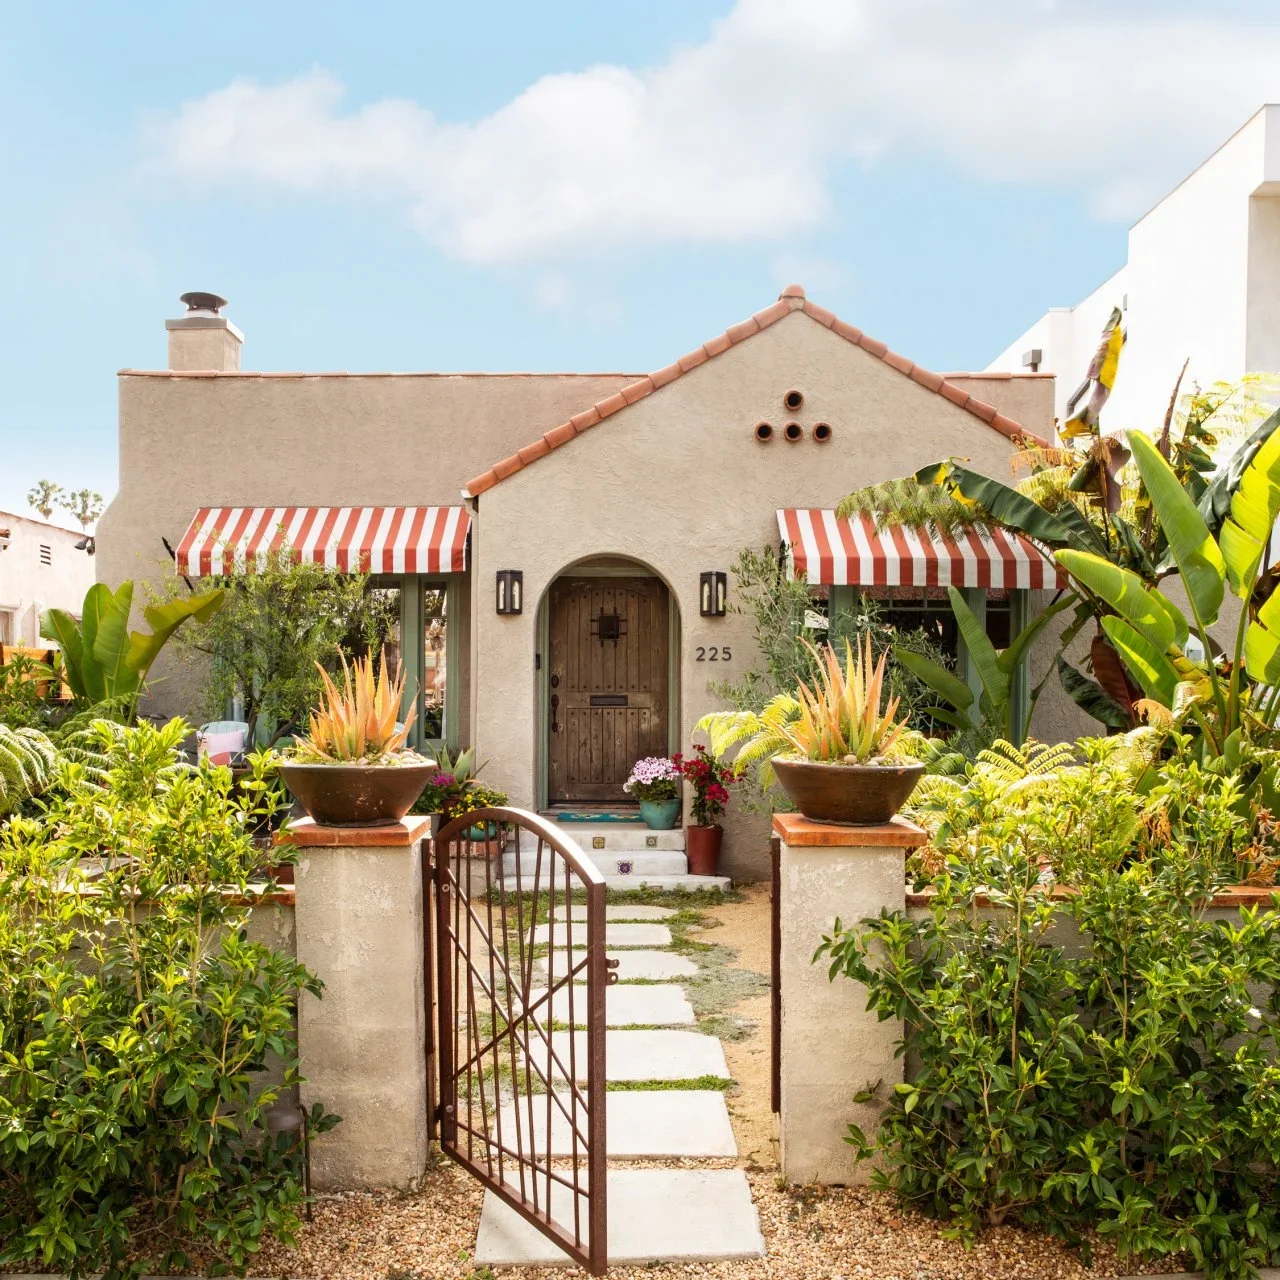
See my favorite homes on the market:
____________________________
Follow along:
____________________________
I love meeting new people! If you want to chat real estate, living in LA, or just a little bit about life, shoot me a note:
dana.pieper@sothebys.realty
____________________________